Commercial Loans for Income Property and Owner-User Buildings
Are you a Builder?
We Provide financing for new construction projects.Do you have information about your project?
Fill this form to get us started with your commercial loan.Commercial loans for income property and business-use real estate
Commercial financing is underwritten differently from a primary-home mortgage. Lenders look harder at net operating income, debt service coverage, leases, reserves, sponsor experience, and the property type. Summit Lending LLC (NMLS 2394434) helps investors and owner-users compare structures for small residential investment properties, mixed-use buildings, retail and office, and builder inventory.
Our licensed markets are Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Office: 4542 W 14800 N, Garland, UT 84312. Call 385-200-1470 or email [email protected].
What "commercial" can mean on our desk
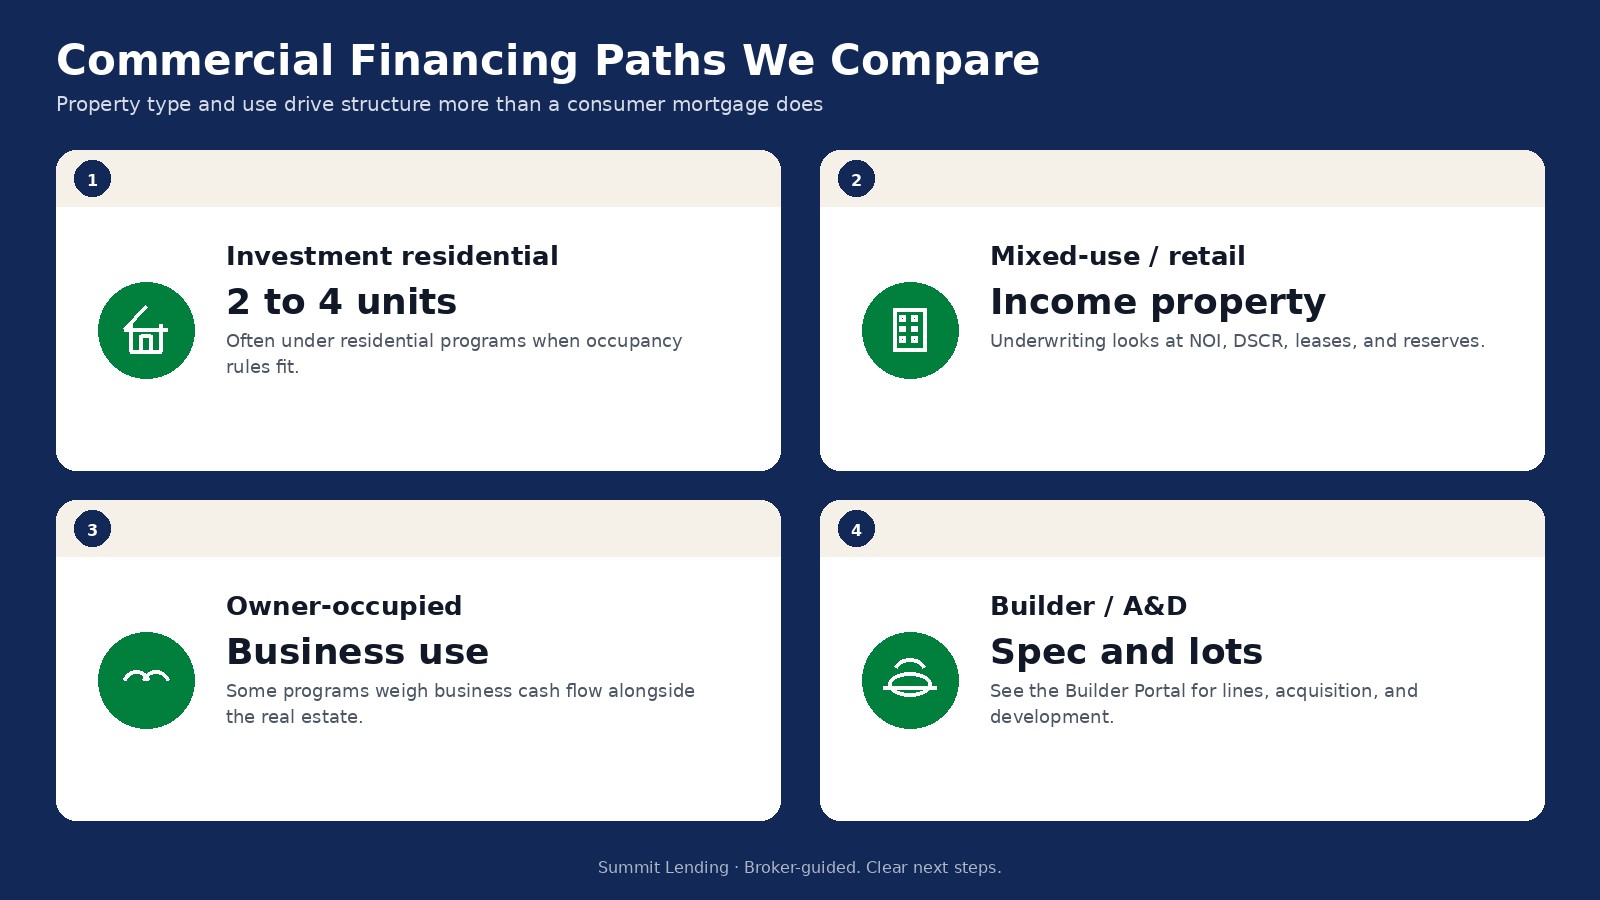
- 1-4 unit investment residential. Some files still fit residential investor programs when occupancy and credit rules allow. Others need a commercial credit box.
- Mixed-use and small commercial. Retail, office, and mixed-use properties usually need income documentation, rent rolls, and a clearer exit plan.
- Owner-occupied business real estate. When your company will operate in the building, some programs weigh business cash flow alongside the real estate.
- Builder and A&D. Spec homes, acquisition, and development belong in the Builder Portal conversation.
If the property will be your primary residence, start with purchase loans instead. If you are extracting equity from a home you live in, see refinance.
How commercial underwriting differs
Consumer mortgages lean on personal credit, income, and the home's appraised value. Commercial files add property cash flow (often measured with debt service coverage), tenant quality, remaining lease term, vacancy assumptions, and reserves for repairs or tenant improvements. Down payment expectations are often higher than on an owner-occupied home. Timelines can run longer because third-party reports (appraisal, environmental, and sometimes a survey) take time.
We will tell you early if a file looks more like a residential investor loan or a true commercial credit. That honesty saves weeks.
State commercial hubs
- Utah commercial loans and Utah mortgages
- Texas commercial loans and Texas mortgages
- Idaho commercial loans and Idaho mortgages
- Wyoming commercial loans and Wyoming mortgages
What to prepare
- Property type, purchase price or refinance balance, and intended use
- Rent roll, leases, and trailing income and expense history when available
- Borrower and entity structure (personal name, LLC, or other)
- Down payment source and liquidity for reserves
- Exit plan: hold period, refinance, or sale
Also see the broader mortgage loans page, construction loans for ground-up projects, and loan calculator for rough payment modeling on simpler residential investor scenarios.
Entity structure and personal guarantees
Many small commercial loans still ask for personal guarantees even when title sits in an LLC. That is normal. What matters is knowing when a guarantee is required, how recourse works, and whether your other real estate or business debt already strains the picture. Bring entity documents, operating agreements, and a simple organizational chart to the first call.
DSCR and vacancy reality
Debt service coverage looks neat on a spreadsheet and messy in a soft rental market. We underwrite with realistic vacancy and repair reserves, not best-case occupancy forever. If the deal only works at perfect rent growth, it is not a resilient deal. That honesty is part of the broker job.
For lighter residential investor scenarios that still fit agency boxes, the purchase and refinance pages may be the better doorway. For ground-up projects, use construction loans.
When residential investor pricing is enough
A clean 1-4 unit rental with solid credit and reserves may never need a full commercial credit box. Pushing every rental into commercial terms can cost more for no benefit. We sort that early. Conversely, a mixed-use building with short-term leases should not pretend to be a simple primary-home refinance.
Information on this page is for general education. It is not a commitment to lend. Loan availability, terms, and pricing depend on your credit, income, assets, property, and lender overlays. Summit Lending LLC, NMLS 2394434.