Utah Mortgage Loans with Local Broker Guidance
Utah mortgages with a broker who shops options
Utah home financing is rarely one-size-fits-all. Prices along the Wasatch Front sit well above the national median, property taxes and insurance vary by county, and the right program depends on your down payment, credit, occupancy, and timeline. Summit Lending LLC (NMLS 2394434) is a Utah-based mortgage broker that matches borrowers to purchase, refinance, construction, reverse, commercial, and builder financing across the state.
We are headquartered at 4542 W 14800 N, Garland, UT 84312, with deep roots in northern Utah and daily work across Salt Lake, Utah, Davis, Weber, Box Elder, Washington, and other counties. Call 385-200-1470 or email [email protected] when you want a real conversation about payment, cash to close, and program fit.
Utah mortgage options we help with
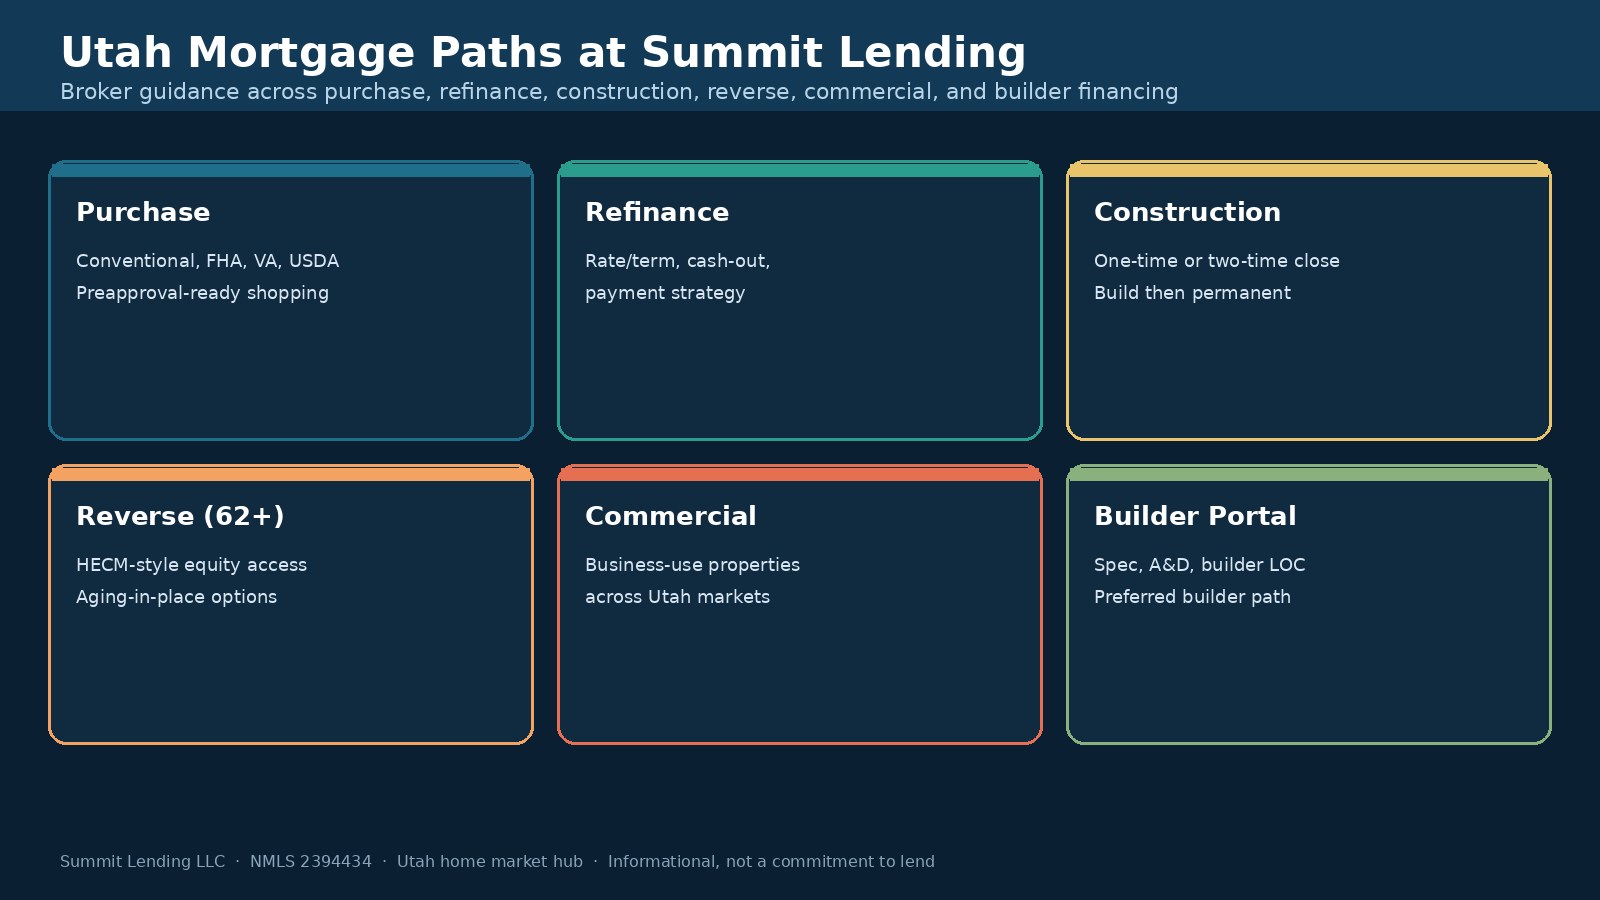
Start with the goal, then pick the product family. These hubs go deeper on each path:
- Purchase loans for buying a primary home, including Conventional, FHA, VA, and USDA structures when you qualify. Utah shoppers often begin here, then move into a county-specific purchase page such as Utah purchase loans.
- Refinance for rate-and-term, payment relief, shorter terms, or cash-out equity. See also Utah refinance when you already own here.
- Construction loans with one-time close and two-time close paths, plus the Utah construction hub at construction loans in Utah.
- Reverse mortgages (HECM-style options for eligible seniors 62+) and the Utah reverse page at Utah reverse mortgages.
- Commercial financing for business-use properties, with a Utah commercial hub at Utah commercial loans.
- Builder Portal for spec financing, acquisition and development, and builder lines of credit when you build for sale or develop lots.
New to homeownership? Pair this page with first-time home buyer resources and the Utah FTHB hub at first-time buyers in Utah.
What Utah buyers and owners should model first
Statewide headlines help, but your payment lives at the county and property level. Before you fall in love with a listing (or a refinance quote), work through:
- Full PITI, not principal and interest alone. Use the mortgage calculator and the Utah calculator at loan calculator for Utah to layer taxes and insurance on top of principal and interest.
- Down payment and reserves. A lower down payment can open more homes and may add mortgage insurance. Keep cash for closing costs, moving, and a maintenance cushion.
- Program fit. Conventional is flexible for many credit and property profiles. FHA can help with lower down payments. VA can remove the down payment requirement for eligible veterans and service members. USDA can fit some rural and suburban Utah locations with 0% down when eligibility lines up.
- How long you will keep the loan or the home. Refinance break-even math and points only make sense against a realistic hold period.
When you are ready to shop with a letter, start preapproval or the Utah preapproval path at Utah preapproval.
County and metro hubs across Utah
Inventory, days on market, and tax stacks differ from Salt Lake County to Utah County, Davis, Weber, Cache, Washington County, and northern Utah communities like Garland and Tremonton. Explore local mortgage hubs:
- Salt Lake County mortgages and Salt Lake County purchase loans
- Utah County mortgages and Utah County purchase loans
- Davis County mortgages
- Weber County mortgages
- Box Elder County mortgages (home base for Summit Lending)
- Washington County mortgages for southern Utah growth markets
- Salt Lake County refinance and Utah County refinance when you already own
City pages such as Salt Lake City, Provo, Ogden, Lehi, and St. George sit under the same Utah tree when you need a tighter geography.
How Summit Lending works with Utah clients
As a broker, we are set up to compare options rather than push a single portfolio product. The process stays simple:
- Connect. Tell us whether you are buying, refinancing, building, accessing equity later in life, or financing a commercial or builder project.
- Weigh options. We translate credit, income, property type, and county realities into a short list of workable programs and payment ranges.
- Start the application. You get a clear document list and timelines instead of a mystery checklist.
- Get to a decision. Underwriting, appraisal, and closing coordination with the goal of fewer surprises on fees and cash to close.
Browse the broader mortgage loans overview if you want the six-state product map. Summit Lending also serves Texas, Idaho, Wyoming, Arkansas, and Arizona, with Utah as our home market.
Utah market context (use carefully)
Utah Association of REALTORS market activity showed a statewide median sales price near $525,000 in August 2026, with inventory still measured in the mid-to-high teens of thousands of listings. Those figures help frame affordability conversations. They are not a quote, an appraisal, or a promise that a specific street will price the same way next month.
Nationally, 30-year fixed averages near 7% in late September 2026 (Freddie Mac weekly survey) keep payment sensitivity high. Model a realistic rate band in the Utah loan calculator, then confirm a personalized quote with a loan officer. We do not invent live rates on this page.
When a Utah mortgage conversation is worth having now
- You want a written preapproval before touring Wasatch Front inventory seriously
- You are comparing Conventional vs FHA vs VA vs USDA on the same Utah property
- You are weighing refinance break-even after closing costs
- You are building new and need one-time or two-time close construction structure
- You are 62+ and evaluating whether a reverse mortgage fits better than a cash-out refinance
- You are a builder or investor who needs commercial or builder financing, not a standard consumer purchase loan
Content on this page is informational and is not a commitment to lend. All loans are subject to credit approval and applicable investor or agency guidelines.
Related next steps
Frequently Asked Questions
Everything you need to know about home mortgage loans in UtahThe perfect loan for you depends on multiple factors, including the following:
- Your risk tolerance
- Your goals long term
- Your monetary situation
A fixed-rate loan is more stable, but an adjustable-rate one might provide financial savings early on. A government-backed loan (e.g., FHA, VA) may be the best option if you have a lower credit score. Our team of experts can help you determine the right Utah mortgage loans for you.
Related Articles
Top Reasons to Refinance Your Mortgage and Why It Works
Utah Mortgage Rates and Housing Market Guide
Mortgage Rates Above 7%: What Utah Buyers Should Do Now (Sept 2026)