Idaho Mortgage Loans with Hands-On Broker Guidance
Idaho mortgages with a broker who compares the options for you
Idaho is not one housing market. A first home in Nampa, a move-up purchase in Ada County, a refinance in Idaho Falls, and a build on acreage outside Coeur d'Alene all ask different questions of a loan. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Idaho, so our job is to put a few workable programs side by side, explain what each one costs you every month and at closing, and help you choose with real numbers instead of guesses.
We are based at 4542 W 14800 N, Garland, UT 84312, in northern Utah's Box Elder County, which shares a border with Idaho. Idaho is one of six states we serve, along with Utah, Texas, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected] when you want to talk through a purchase, a refinance, or a build.
What the Idaho market looks like this fall
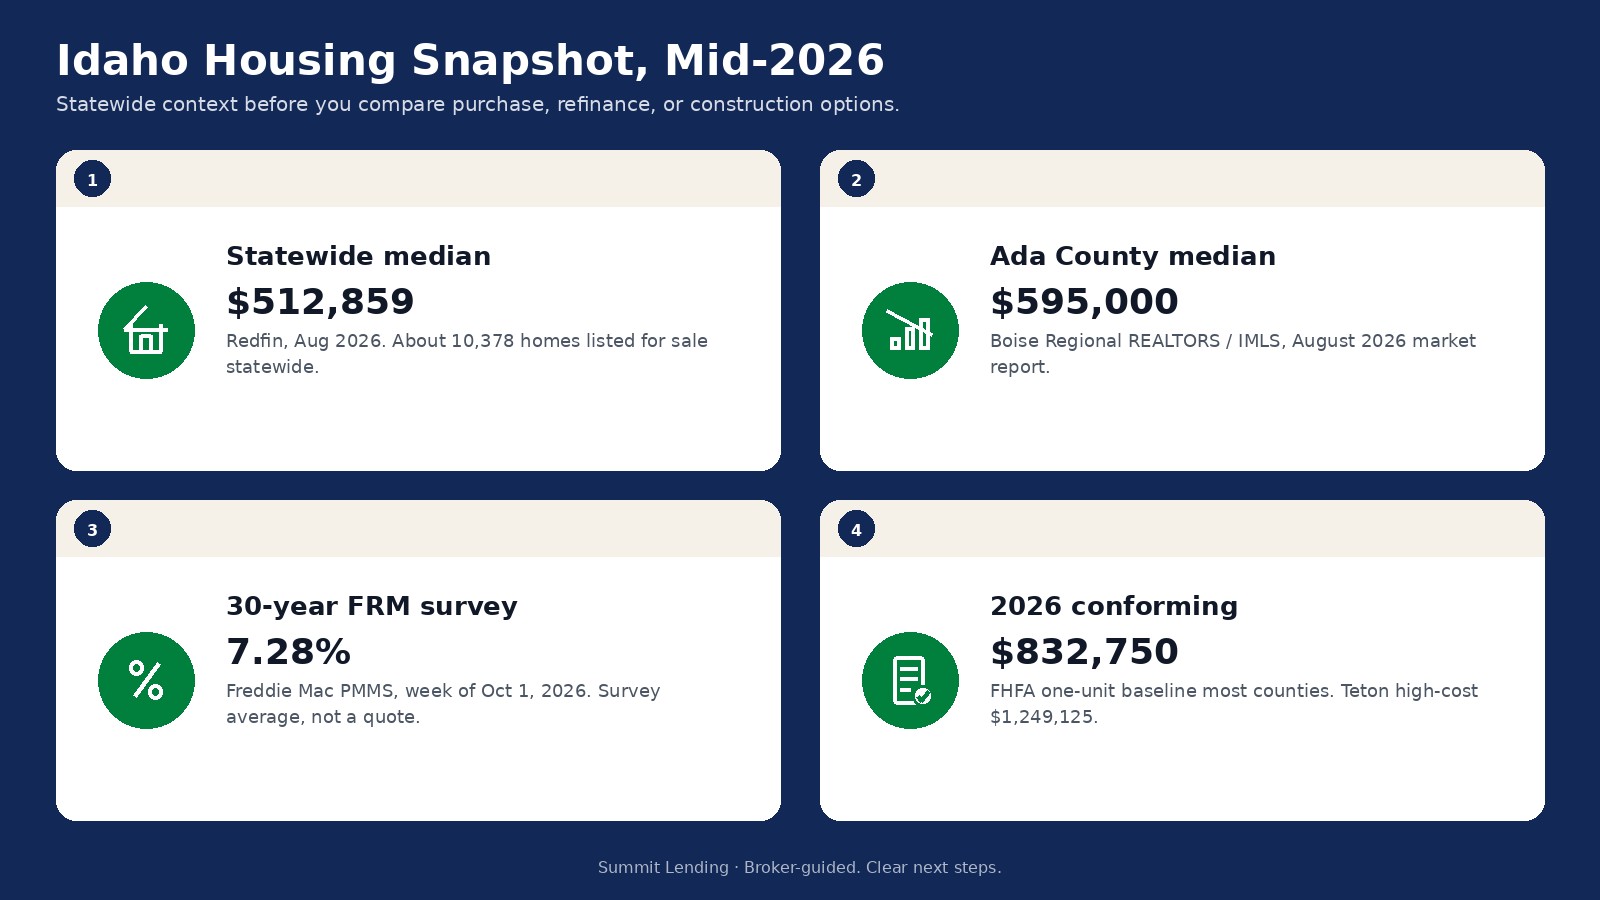
Idaho is still tighter than most of the country. Redfin's August 2026 data put the statewide median sale price at $512,859, up 7.9% from a year earlier. Homes sold rose 10.1% to 2,758, while homes for sale fell 16.1% to 10,378, which works out to roughly three months of supply. The median home went under contract in about 48 days, and around 16% of homes sold above list price.
The Treasure Valley runs higher than the state as a whole. Boise Regional REALTORS reported an Ada County single-family median of $595,000 for August 2026 (Intermountain MLS data), compared with $556,522 in August 2025. Canyon County, Bonneville County, and the Magic Valley generally price lower, while Kootenai, Bonner, Blaine, Valley, and Teton counties can run well above the state median.
Rates moved the wrong way for buyers in late September. Freddie Mac's Primary Mortgage Market Survey showed the 30-year fixed averaging 7.28% for the week of October 1, 2026, up from 7.03% the week before and 6.34% a year earlier. The 15-year fixed averaged 6.60%. Realtor.com described it as the highest level in nearly three years. These are national survey averages for well-qualified borrowers putting 20% down. They are useful for modeling, but they are not a quote from Summit Lending and your rate depends on your credit, loan type, down payment, and the day you lock.
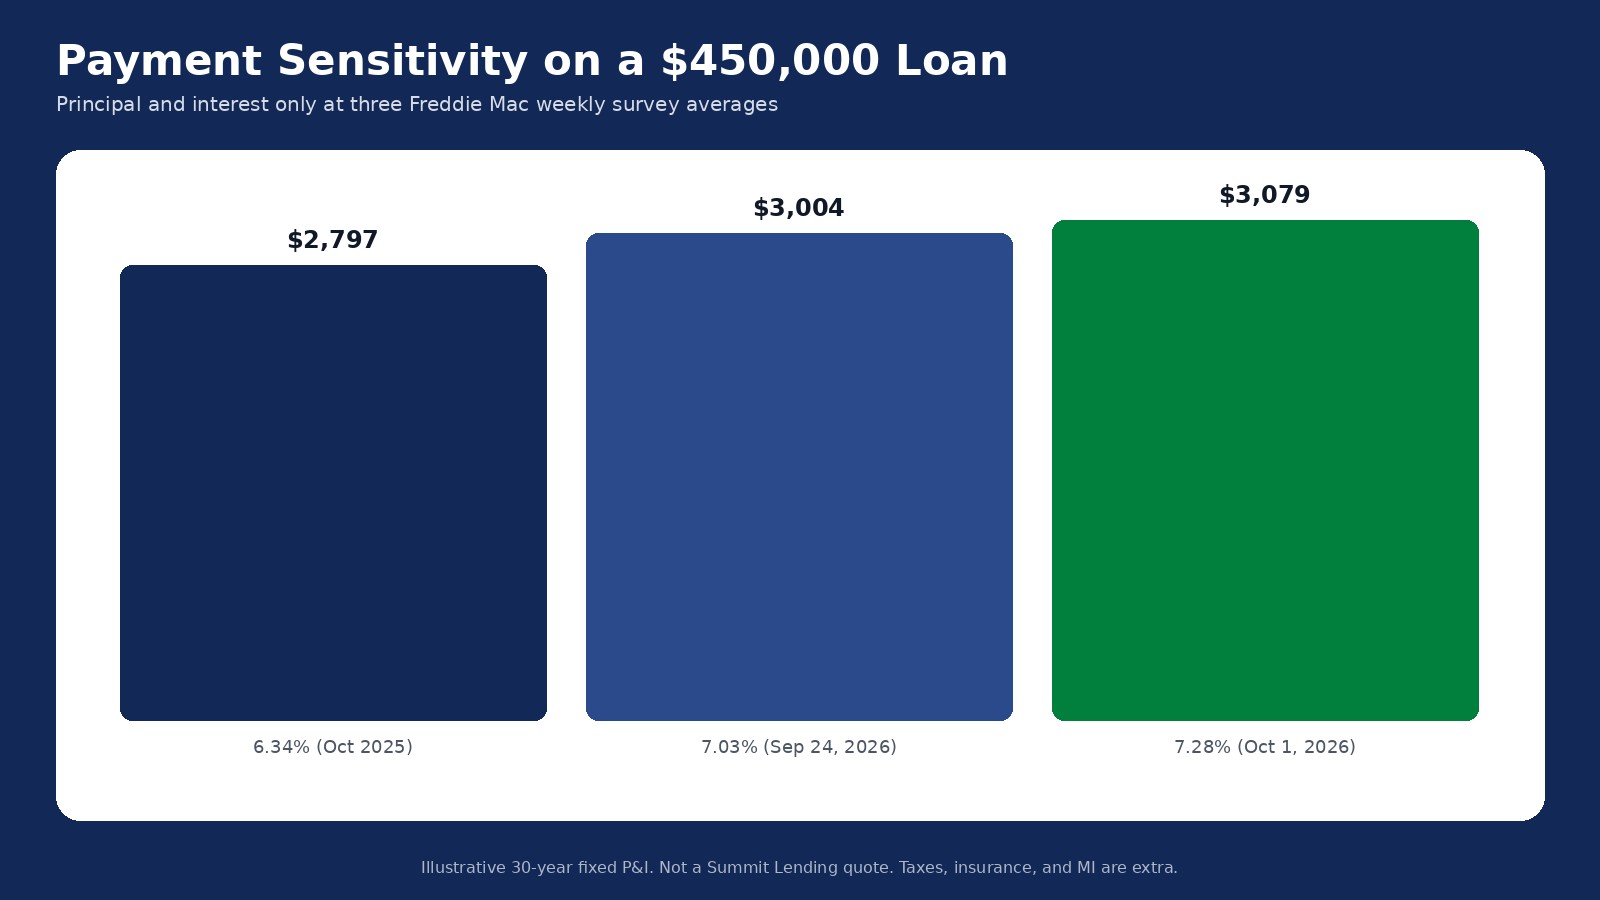
On a $450,000 loan, the jump from 6.34% to 7.28% adds about $282 a month in principal and interest. That is why we start almost every Idaho conversation with a payment range rather than a price range. Plug your own numbers into the Idaho mortgage calculator, then let us check them against your actual credit and property.
Idaho mortgage options we help with
- Idaho purchase loans for primary homes, second homes, and some investment properties, using Conventional, FHA, VA, or USDA structures when you qualify. The national overview lives on our purchase loans page.
- Idaho refinance for a lower payment when the math works, a shorter term, moving off an adjustable rate, or a cash-out refinance. See how we think about break-even on the main refinance page.
- Idaho construction loans with one-time close and two-time close paths for building on your own lot or with a builder. The full explainer is on construction loans.
- Idaho first-time home buyer guidance, including low down payment programs and how down payment assistance fits.
- Idaho reverse mortgages (HECM-style options for homeowners 62 and older) when staying put matters more than moving. Background is on our reverse mortgage page.
- Idaho commercial loans for business-use and investment property, and the Builder Portal for spec homes, acquisition and development, and builder lines of credit.
Programs and loan limits Idaho buyers ask about
Conventional loans and the 2026 limit. FHFA set the 2026 baseline conforming loan limit for a one-unit home at $832,750. That baseline applies in 43 of Idaho's 44 counties. Teton County, which sits in the Jackson, WY-ID metro area, carries the high-cost ceiling of $1,249,125. Loans above the limit for your county move into jumbo territory, where down payment, reserve, and credit expectations usually tighten.
FHA, VA, and USDA. FHA can work with a smaller down payment and more flexible credit. VA can remove the down payment requirement for eligible veterans and service members, which matters near Mountain Home Air Force Base and across the state. USDA Rural Development loans can offer 0% down in eligible areas, and a lot of Idaho outside the largest cities qualifies on location. Income limits and property rules still apply.
Idaho Housing and Finance Association programs. IHFA brought back its First Loan Tax-Exempt program in 2026, with locks available from March 9, 2026, for first-time buyers (repeat buyers can qualify in targeted counties). New county income and sales price limits took effect for reservations on or after May 1, 2026. IHFA's second mortgage can cover down payment and closing costs up to 8% of the lesser of the price or appraised value, at a fixed rate 2% above the first mortgage over 15 years, with at least $500 of your own funds and the Finally Home! homebuyer course required. If an IHFA program looks like the better fit for you, we will say so and help you compare it honestly with the loans we can arrange.
Idaho county and city mortgage guides
Price, inventory, property taxes, and even which loan programs are available can change from one county line to the next. Start with the area you are shopping in:
- Treasure Valley: Ada County mortgages (with Ada County purchase loans and Ada County refinance), Canyon County mortgages and Canyon County purchase loans, plus city pages for Boise, Nampa, Caldwell, Kuna, and Star.
- North Idaho: Kootenai County and Bonner County, with Coeur d'Alene, Post Falls, and Sandpoint.
- East Idaho: Bonneville County, Bannock County, Madison County, and Teton County, with Idaho Falls, Pocatello, and Rexburg.
- Magic Valley and central Idaho: Twin Falls County and Twin Falls, plus Blaine County and Valley County, where resort-area prices change the math.
Buying in Idaho: what to line up before you tour
- A real preapproval. With roughly three months of supply statewide and some homes still drawing multiple offers, sellers want to see a letter backed by verified income and credit. Start with Idaho preapproval (or the general preapproval page).
- The full payment, not just principal and interest. Property taxes, homeowners insurance, mortgage insurance, and any HOA dues can add hundreds a month. If the home will be your primary residence, ask your county assessor about the homeowner's exemption, because it changes the tax bill you should model.
- Cash to close and reserves. Down payment is only part of it. Plan for closing costs, prepaid taxes and insurance, moving, and a cushion for the first repairs.
- A program short list. Compare Conventional, FHA, VA, USDA, and IHFA options on the same house so you can see which one actually costs less over the years you expect to own it.
Refinancing, building, and later-life options in Idaho
If you bought or refinanced when rates were higher than today's survey averages, a rate-and-term refinance can still make sense. If your current rate is below the market, a full refinance usually does not, and the conversation turns to whether you need cash at all and what the cheapest way to get it is. We run the break-even math with you on the Idaho refinance page and the mortgage calculator.
Building is common in Idaho, from subdivision lots in Canyon County to rural parcels in the Magic Valley. A one-time close loan rolls construction and the permanent mortgage into a single closing. A two-time close splits them so you can shop the permanent loan when the house is done. Builders, and anyone weighing a lot purchase, should look at Ada County construction loans, Canyon County construction loans, or the statewide Idaho construction page.
Homeowners 62 and older who want to stay in their home sometimes compare a reverse mortgage with a cash-out refinance or a sale. Those are very different tools, and we walk through the tradeoffs before anyone signs.
How Summit Lending works with Idaho borrowers
- Talk first. Tell us what you are trying to do, where, and when. A short call usually rules out the programs that do not fit.
- Compare options. We translate your credit, income, assets, and the property into a few loan options with payment and cash-to-close estimates.
- Apply with a clear checklist. You get a specific document list and timeline, not a vague request for "everything."
- Close with fewer surprises. We coordinate appraisal, underwriting, and title so the numbers at closing match what we talked about.
Talk with an Idaho mortgage broker
Call 385-200-1470, email [email protected], or start an Idaho preapproval. If you are still early, the first-time home buyer guide and the mortgage loans overview are good places to start.
Summit Lending LLC, NMLS 2394434, 4542 W 14800 N, Garland, UT 84312. Market figures and rates on this page are cited from third-party sources for general information and may change. This page is informational and is not a commitment to lend. All loans are subject to credit approval, property eligibility, and program guidelines.
Related Idaho pages
Frequently Asked Questions
Everything you need to know about home mortgage loans in IdahoSeveral factors dictate which mortgage loan will work best for you, including your risk tolerance, long-range goals, and financial circumstances. A fixed-rate mortgage is stable, while an adjustable-rate one will provide monetary savings starting out. A government-backed loan may be an excellent choice if you have a lower credit score. Let your Summit Lending partners help you determine the right option for your unique needs.
Related Articles
ARM or Fixed at 7.28%? An Idaho Homebuyer's Guide (October 2026)
Freddie Mac's 30-year fixed hit 7.28% on Oct. 1, 2026, and ARMs climbed to 10.3% of applications. Here is how a 5-year ARM really compares with a fixed loan on a $595,000 Ada County home, including resets, caps, and the qualifying rule most buyers miss.
New Construction vs. Resale in Idaho at 7.40%: How to Compare Builder Incentives (Oct 2026)
Freddie Mac's 30-year average hit 7.40% on Oct. 8, and September MLS data put Ada County's new construction median about $61,600 above resale. Here is how to price a builder's rate buydown or cash credit against a resale home, with Treasure Valley numbers and the Idaho tax rules that change a new-build budget.