Idaho Commercial Real Estate Loans
Are you a Builder?
We Provide financing for new construction projects.Do you have information about your project?
Fill this form to get us started with your commercial loan.Commercial real estate loans in Idaho
A commercial mortgage finances property used for business or income: an office or warehouse your company occupies, a retail strip, a mixed-use building, a five-plus-unit apartment complex, or land you plan to develop. Unlike a home loan, a commercial loan is underwritten mostly on the property's income and the borrower's business strength, and the terms are negotiated rather than standardized. Summit Lending LLC (NMLS 2394434) is a broker that helps Idaho owners and investors compare commercial options, from bank loans to SBA programs, and package a request lenders can say yes to.
Idaho's commercial growth is led by the Treasure Valley, where Boise, Meridian, and Nampa have added industrial, flex, medical, and retail space. Coeur d'Alene and Kootenai County, Idaho Falls, Pocatello, and Twin Falls add regional retail, hospitality, agriculture-related, and owner-occupied business property. See local pages for Boise, Nampa, and Idaho Falls.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The main commercial loan paths
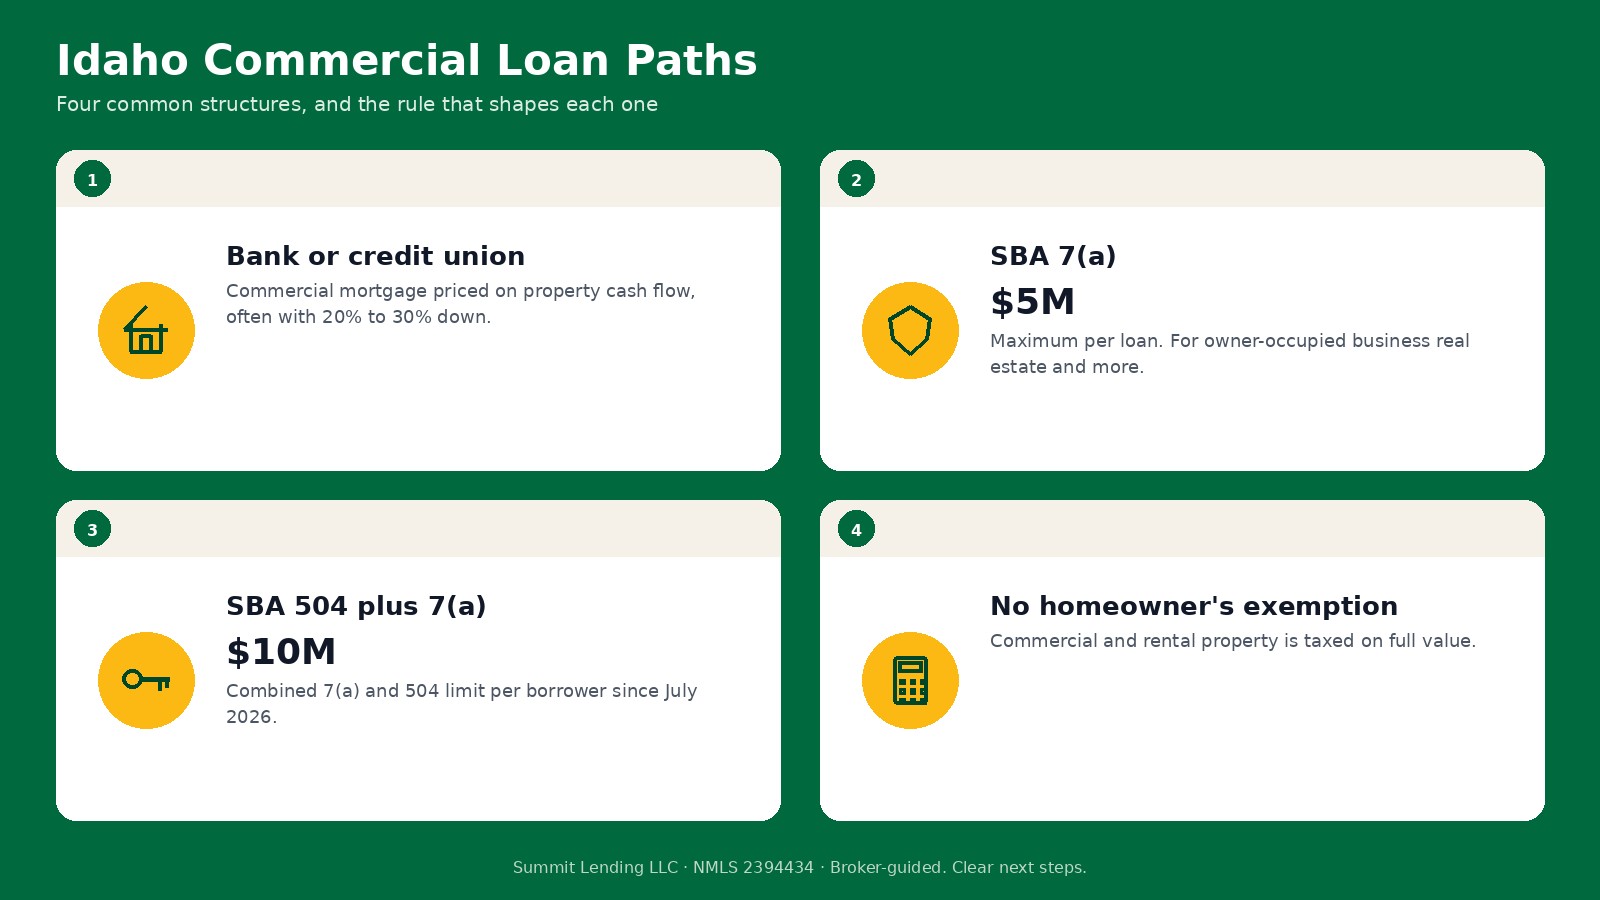
- Bank and credit union loans. The most common choice for stabilized property. Expect a down payment of roughly 20% to 30%, a term of 5 to 10 years, and amortization of 20 to 25 years, often with a balloon at the end. Lenders size the loan on debt service coverage, which is the property's net operating income divided by the annual loan payment.
- SBA 7(a). For owner-occupied business property, equipment, working capital, and business acquisitions. The maximum 7(a) loan is $5 million (SBA 7(a)), and real estate terms can run up to 25 years. Your business generally must occupy at least 51% of an existing building.
- SBA 504. Built for owner-occupied real estate and major fixed assets. A typical structure is a bank first mortgage for about 50% of the project, a Certified Development Company loan for up to 40% at a long-term fixed rate, and about 10% from the borrower (SBA 504). As of July 2026, a small business can hold up to $10 million in combined 7(a) and 504 financing (SBA announcement).
- Investor and bridge loans. For non-owner-occupied property, value-add projects, or quick closings. Debt service coverage ratio (DSCR) loans on one to four unit rentals, and bridge loans on commercial property, trade higher rates for flexibility.
How lenders size a commercial loan
Two numbers usually set the limit: loan-to-value and debt service coverage. Many lenders look for coverage of at least 1.20 to 1.25 times, which means the property's net operating income is 20% to 25% higher than the annual payment. Here is a simple example at an illustrative 7.50% rate on a 25-year amortization:
- Purchase price: $1,500,000. Net operating income: $120,000 a year.
- At 75% loan-to-value, the loan is $1,125,000 and the annual payment is about $99,764.
- Coverage is $120,000 divided by that payment, about 1.20 times, which falls short of 1.25. At about $1,000,000 the coverage clears 1.25, so the buyer would need more cash or a higher income property.
Rates are moving. The 30-year residential average was 7.40% for the week of October 8, 2026, up from 6.30% a year earlier (AP report on the Freddie Mac survey). Commercial rates are priced differently, usually off Treasury yields or bank indexes, but the same pressure applies. Test your numbers at a rate higher than the one you are quoted.
No homeowner's exemption on commercial property
Idaho's homeowner's exemption applies only to an owner-occupied primary residence. Commercial, industrial, and investment property is taxed on full market value, so use the full assessed value from the county assessor when you underwrite a purchase. (official source)
What to have ready
- Property documents. Rent roll, current leases, two to three years of operating statements, and the purchase contract or current mortgage statement.
- Business and personal financials. Two to three years of business and personal tax returns, a current profit and loss statement and balance sheet, and a personal financial statement for each owner with 20% or more.
- Entity documents. Articles of organization, operating agreement, and good standing. Most commercial loans are made to an LLC or corporation with personal guarantees from the owners.
- Project details. For construction or renovation, a budget, plans, and contractor bids. For a business purchase, the seller's financials and a business plan.
Idaho commercial loan, step by step
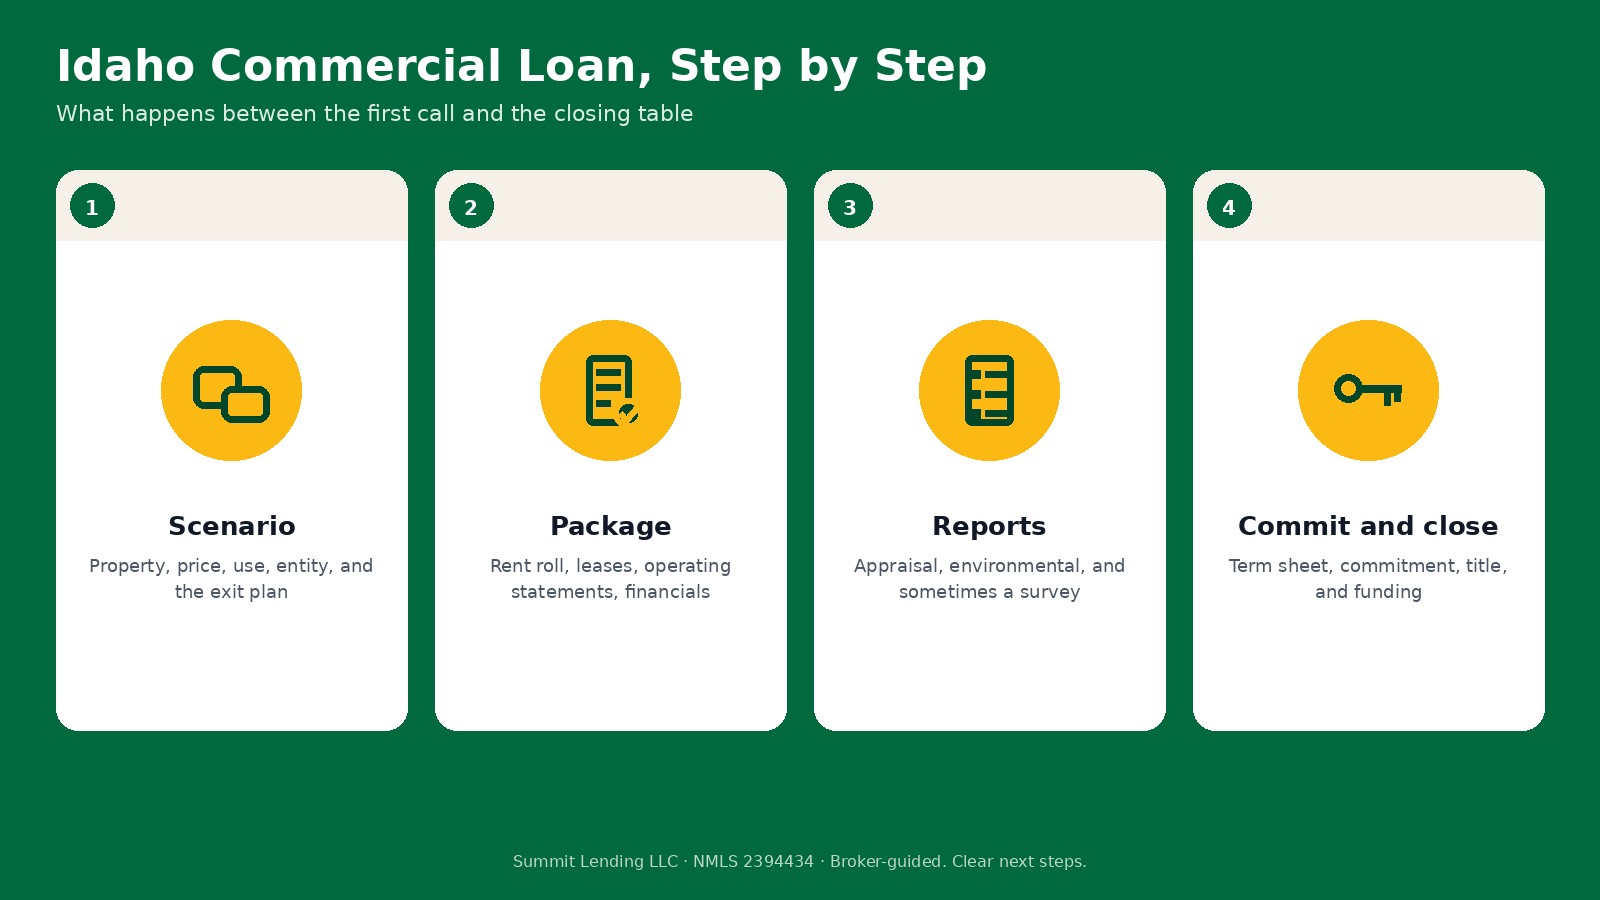
- Scenario. We review the property, price, use, entity, and how long you plan to hold, then identify which loan paths fit.
- Package and term sheets. We assemble the loan package and request term sheets from lenders. Compare rate, fees, prepayment penalties, recourse, and covenants, not just the rate.
- Third-party reports. A commercial appraisal, usually an environmental site assessment, and sometimes a survey or property condition report. Expect three to six weeks.
- Commitment and closing. The lender issues a commitment with conditions, title and insurance are finalized, and the loan funds. Plan on 45 to 90 days from application, and longer for SBA or construction loans.
Common questions we help Idaho borrowers sort out
- Five-plus-unit apartments are commercial loans, while one to four units can use residential financing. See Idaho purchase loans.
- Mixed-use buildings with ground-floor retail and apartments above can go either way, depending on the commercial share.
- Refinancing a maturing balloon loan is one of the most common requests right now. Start six months before maturity.
- Prepayment penalties such as step-downs or yield maintenance can make an early sale or refinance expensive. Read them before you sign.
Idaho commercial lending by area
Cities: Boise, Nampa, Idaho Falls, Pocatello, Coeur d’Alene, and Twin Falls. Counties: Ada County, Canyon County, Kootenai County, Twin Falls County, and Teton County.
Related pages
See the national commercial loans page, commercial lending in Utah, Texas, Wyoming, the Idaho mortgage overview, the Idaho refinance page, and the Idaho mortgage calculator.
Sources
- SBA, 7(a) loans
- SBA, 504 loans
- SBA, small businesses now eligible for $10 million in SBA financing
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Idaho State Tax Commission, homeowner's exemption
- Redfin, Idaho housing market
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.