Want to get prequalified?
We can help you navigate the pre-approval process all the way to the finish line, with a letter sellers take seriously.
Get pre-approvedReverse mortgages in Wyoming: how a HECM works here
A reverse mortgage lets a Wyoming homeowner who is 62 or older turn part of their home equity into cash without a monthly mortgage payment. It can supplement retirement income, pay off an existing mortgage, cover a long winter of heating bills and repairs, or set up a line of credit for later. It is still a loan. Interest and insurance are added to the balance every month, and you keep paying property tax, insurance, and upkeep for as long as you live in the home. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming. We explain the federal rules, the costs, and the Wyoming tax programs that sit alongside a reverse mortgage, and we encourage families to join the conversation.
Most reverse mortgages are Home Equity Conversion Mortgages, or HECMs, insured by the Federal Housing Administration. This page focuses on HECMs and the 2026 federal limits.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
The basics
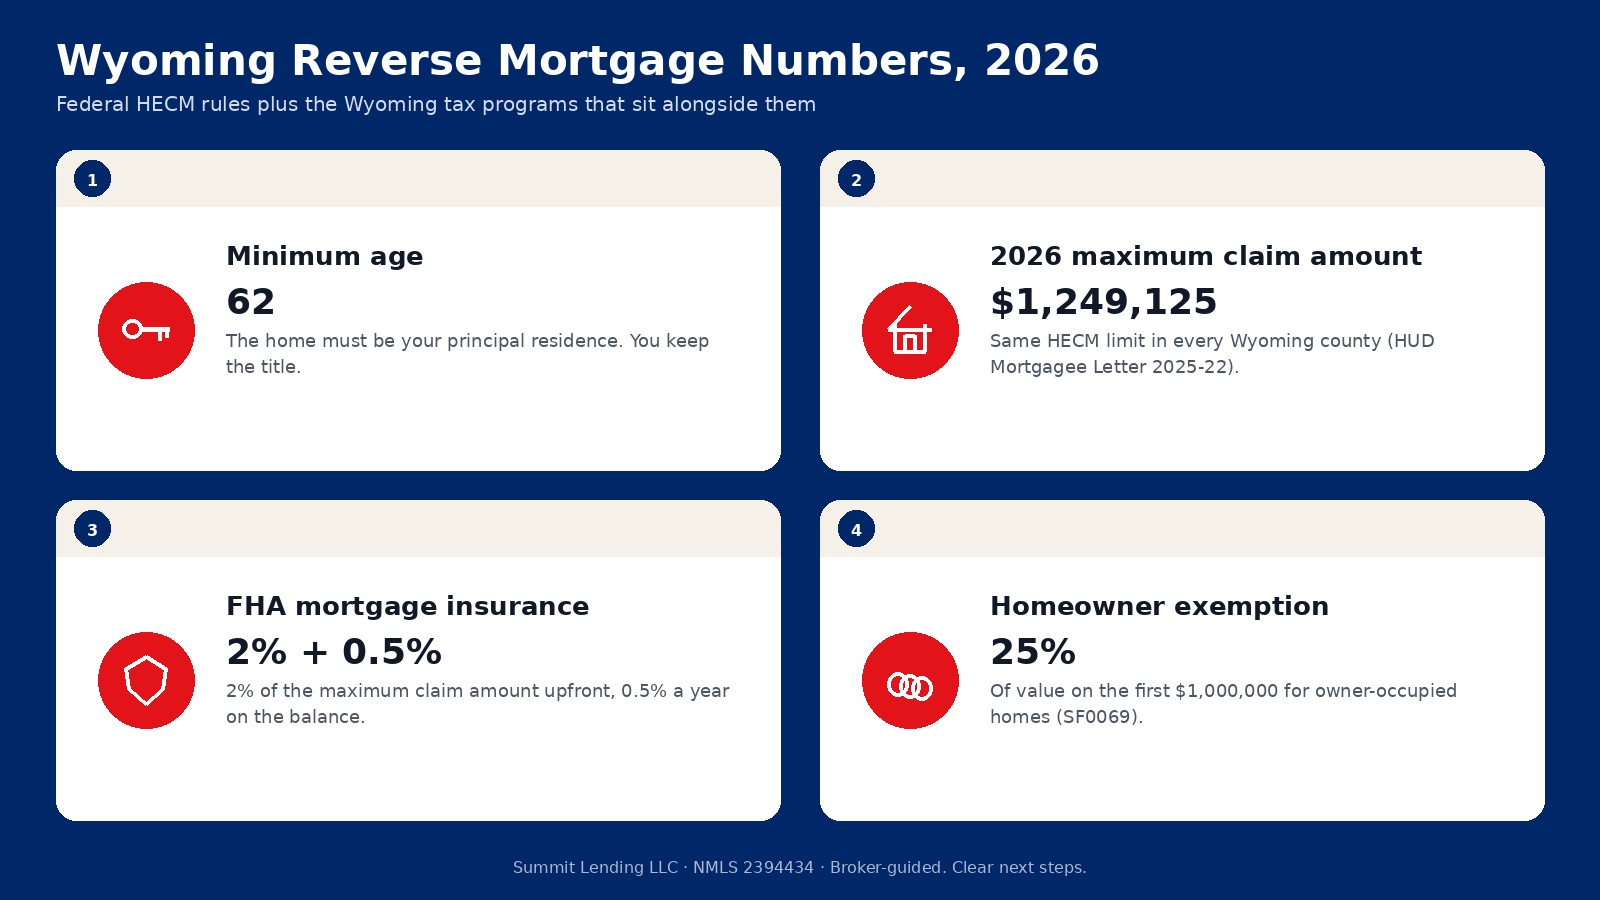
- Age and occupancy. At least one borrower must be 62 or older, and the home must be your principal residence (CFPB on reverse mortgages).
- No monthly mortgage payment. Interest and mortgage insurance are added to the balance instead, so what you owe grows over time.
- You keep the title. You still own the home and remain responsible for property tax, homeowners insurance, HOA dues, and maintenance. Falling behind on those can put the loan in default (CFPB).
- Non-recourse. With a HECM, you or your heirs never owe more than the home is worth when the loan is repaid. FHA insurance covers any shortfall.
- When it is repaid. The loan usually comes due when the last borrower dies, sells the home, or no longer lives there as a principal residence, including more than 12 consecutive months away for health reasons.
2026 HECM limits and insurance
For 2026, the HECM maximum claim amount is $1,249,125 in every county, including all of Wyoming, up from $1,209,750 in 2025 (HUD Mortgagee Letter 2025-22). The maximum claim amount is the lower of your appraised value or that limit. FHA charges an upfront mortgage insurance premium of 2% of the maximum claim amount and an annual premium of 0.5% of the outstanding balance (HUD Mortgagee Letter 2017-12).
A Wyoming example. Redfin put the statewide median sale price at about $394,865 for September 2026, up 8.9% from a year earlier (Redfin Wyoming data). On a home appraised at $395,000, the upfront premium would be about $7,900. In a higher-priced market such as Teton County, a home appraised above the limit is capped at 2% of $1,249,125, about $24,982. Most borrowers finance the premium and other closing costs into the loan, which reduces the cash available but avoids paying them out of pocket.
How much you can receive depends on the age of the youngest borrower (or eligible non-borrowing spouse), the expected interest rate, and the maximum claim amount. Older borrowers and lower rates generally mean more available proceeds. Rates are higher than a year ago: the 30-year fixed survey average was 7.40% for the week of October 8, 2026, versus 6.30% a year earlier (AP report on the Freddie Mac survey; Freddie Mac PMMS).
How you can take the money
Federal HECM rules set out the payment options (24 CFR 206, Subpart B):
- Term. Equal monthly payments for a fixed number of months.
- Tenure. Equal monthly payments for as long as the loan stays in good standing and you live in the home.
- Line of credit. You draw money when you want it, up to your available limit. The unused portion grows over time.
- Modified term or modified tenure. Monthly payments combined with a line of credit.
- Single lump sum. One payment at closing. This is the only option for a fixed-rate HECM.
Any existing mortgage must be paid off from the proceeds first. If required repairs are found, the lender sets aside 150% of the estimated cost. If the financial assessment shows a risk that taxes or insurance could go unpaid, the lender can set aside part of your funds to pay them for you (24 CFR 206.19).
Wyoming property tax programs that fit alongside a reverse mortgage
Wyoming has no state income tax, so property tax and insurance are the main ongoing costs of staying in your home. Residential property is assessed at 9.5% of its fair market value (Wyoming Property Tax Division), and the state has added relief programs that can lower the bill a reverse mortgage requires you to keep paying.
- Owner-occupied exemption. Starting with 2025 legislation, a qualifying owner-occupied home is exempt on 25% of its fair market value, applied to the first $1,000,000 of value. You must own and live in the home at least eight months of the year and apply through your county assessor or the state portal (Wyoming SF0069 summary; application portal).
- Property Tax Refund Program. The Department of Revenue refunds part of the property tax paid by eligible residents. You must have lived in Wyoming at least five years, occupied the home as your principal residence at least nine months of the year, meet income limits tied to the county or state median, and have assets below the program limit, which excludes the home itself and retirement accounts. Applications are due by the first Monday in June (Wyoming Department of Revenue; filing instructions).
- Veterans exemption. Eligible Wyoming veterans can claim a property tax exemption through their county treasurer.
Apply for these before or during your reverse mortgage application. They lower the tax line in the lender's financial assessment, which can reduce any required set-aside and leave more of your equity available.
Costs and Wyoming realities to plan for
- Insurance. Homeowners insurance must stay in force. Hail, wind, and wildfire risk have pushed premiums up in parts of Wyoming. Budget for increases over time.
- Repairs and winters. The home has to be maintained. Roofs, furnaces, and well or septic systems in rural areas are common inspection items. Required repairs are handled through a set-aside at closing.
- Rural and unusual properties. Homes on acreage, manufactured homes, and properties with outbuildings can qualify but need an appraisal that supports value. Manufactured homes must meet FHA standards, including a permanent foundation.
- Time away. Spending winters elsewhere is fine as long as the Wyoming home remains your principal residence. Ask before you plan an extended absence.
What families should understand
The CFPB puts it plainly: a reverse mortgage is not free money. The balance rises while equity falls, and the loan is usually repaid by selling the home once the last borrower no longer lives there (CFPB). Any equity left after repayment belongs to you or your heirs. Heirs can also pay off the loan and keep the home. A non-borrowing spouse may be able to stay in the home after the borrower dies if they meet HUD's requirements, so include them in counseling.
How a Wyoming reverse mortgage moves
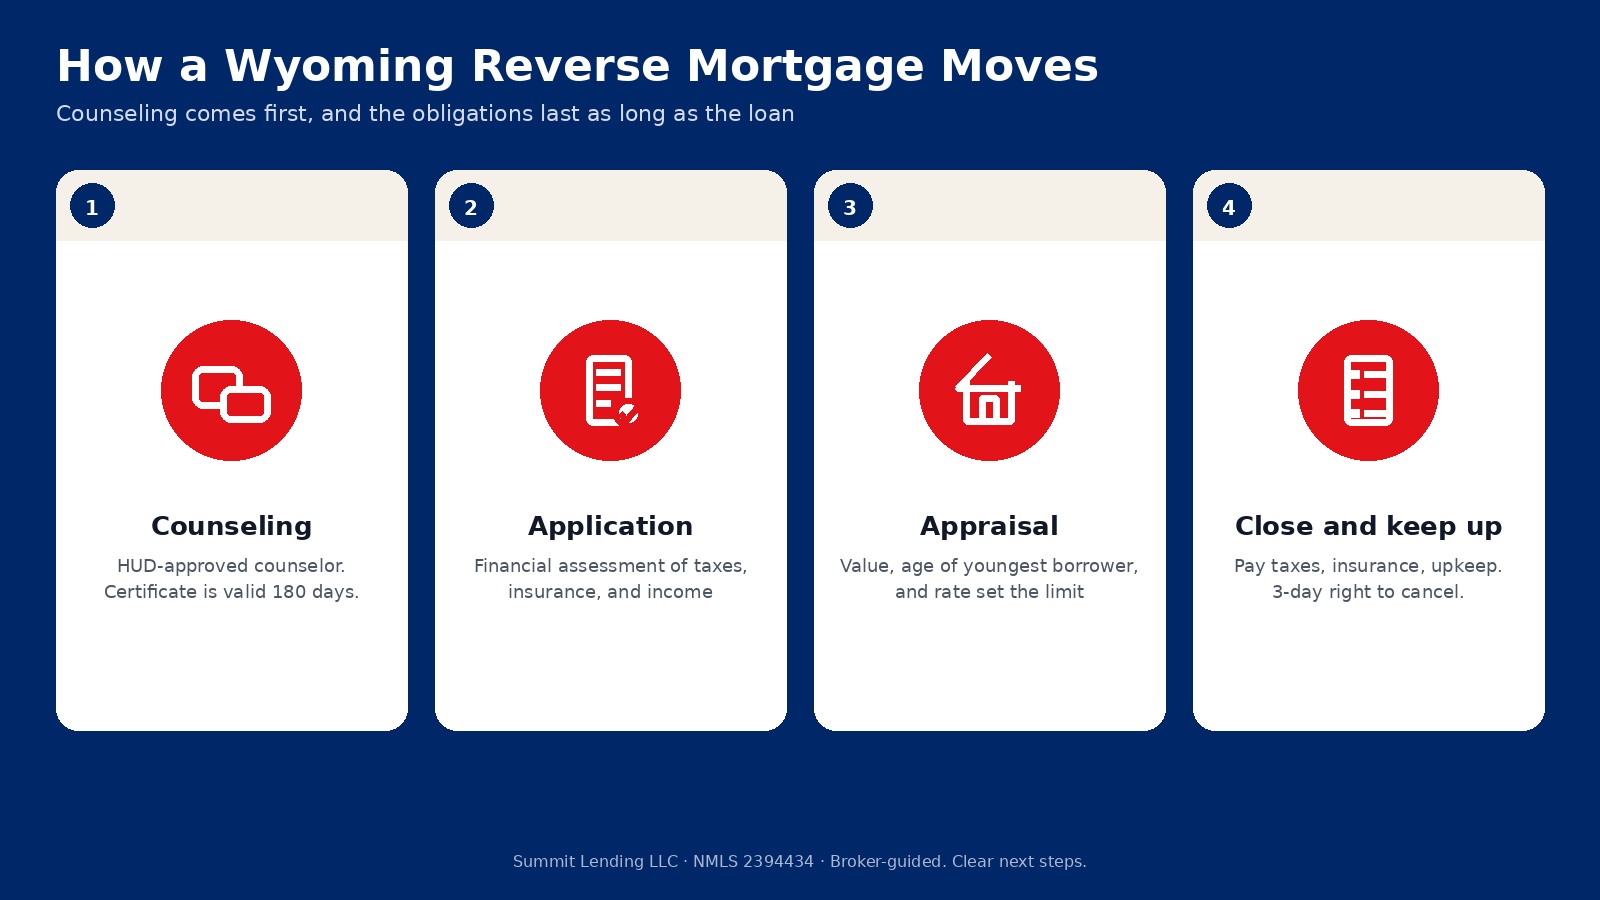
- Counseling. You meet with a HUD-approved HECM counselor who is independent of the lender (HUD HECM overview; find counselors through HUD housing counseling). Sessions by phone are common and practical in rural Wyoming.
- Application and financial assessment. The lender reviews credit, income, and your ability to keep paying taxes and insurance.
- Appraisal. An FHA appraisal sets the value. With the youngest borrower's age and the rate, it determines how much is available.
- Closing and the right to cancel. For most reverse mortgages you have three business days after closing to cancel (CFPB). After that, you keep up with taxes, insurance, and maintenance for the life of the loan.
Is a reverse mortgage right for you?
It can make sense if you plan to stay in your home for many years, have significant equity, and want to reduce monthly costs or build a cushion. It may not fit if you expect to move soon, want to leave the full value of the home to heirs, or would struggle to keep up with taxes and insurance. Alternatives include downsizing, a traditional Wyoming refinance, the state refund program, or a home equity loan. Talk to us and to a counselor before deciding (CFPB guide).
Where we help Wyoming homeowners
Cities: Cheyenne, Casper, Laramie, Gillette, Rock Springs, Teton Village, and Cody. Counties: Laramie County, Natrona County, Campbell County, Sweetwater County, Albany County, Teton County, and Sheridan County.
Related pages
See Utah reverse mortgages, Idaho reverse mortgages, Texas reverse mortgages, or the national reverse mortgage page. For Wyoming, the Wyoming mortgage overview, Wyoming mortgage calculator, Wyoming purchase loans, and Wyoming preapproval cover the rest.
Sources
- CFPB, What is a reverse mortgage?
- HUD Mortgagee Letter 2025-22, 2026 HECM limits (PDF)
- HUD Mortgagee Letter 2017-12, HECM premiums (PDF)
- HUD HECM origination and servicing overview (PDF)
- 24 CFR Part 206, Subpart B, HECM eligibility and payment options (PDF)
- HUD housing counseling
- Redfin, Wyoming housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac Primary Mortgage Market Survey
- Wyoming DOR Property Tax Division, residential
- Wyoming Legislature, 2025 SF0069 bill summary (PDF)
- Wyoming owner-occupied exemption application
- Wyoming Department of Revenue, Property Tax Refund Program
- Wyoming Property Tax Refund, filing instructions
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.