Wyoming First-Time Home Buyers

Get A Mortgage Loan And Unlock Your First Home in Wyoming
Buying your first home is life-changing, and it's only natural for you to want to take the big step without any uncertainties. At Summit Lending, we help first-time home buyers navigate the process of finding the best mortgage loan in Wyoming.
With us, you won't have to worry about struggling with mortgage payments or refinancing in the future. We help you get it right the first time.
Want to get prequalified?
We can help you navigate the pre-approval process all the way to the finish line, with a letter sellers take seriously.
Get pre-approvedBuying your first home in Wyoming
Wyoming has one of the friendlier setups in the region for first-time buyers. Prices are below many neighboring states, the state housing agency offers low fixed-rate loans with down payment help, and a 2025 law cut property tax on owner-occupied homes. The catch is that each program has its own rules about income, price, credit, and education, and the order you do things in matters. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming, based in Garland, Utah. We compare loans from multiple wholesale lenders and help you see which programs fit before you make an offer.
Ready to see your numbers? Start a Wyoming preapproval or estimate a payment with the Wyoming mortgage calculator.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Wyoming prices and rates right now
Redfin put Wyoming's statewide median sale price at about $387,387 for August 2026 (Redfin Wyoming data). Prices vary widely: homes in Casper and Rock Springs often cost well under that, while Teton County is in a different market entirely. Freddie Mac's survey put the 30-year fixed average at 7.28% for the week of October 1, 2026, up from 6.34% a year ago, with the 15-year at 6.60% (Freddie Mac PMMS).
On a $387,000 home with 3.5% down on an FHA loan, the base loan is about $373,455. At 7.28%, principal and interest on that base is about $2,555 a month, before FHA insurance, taxes, and homeowners insurance. Run your own figures with the calculator and treat the survey rate as a starting point, not a quote.
Who counts as a first-time buyer
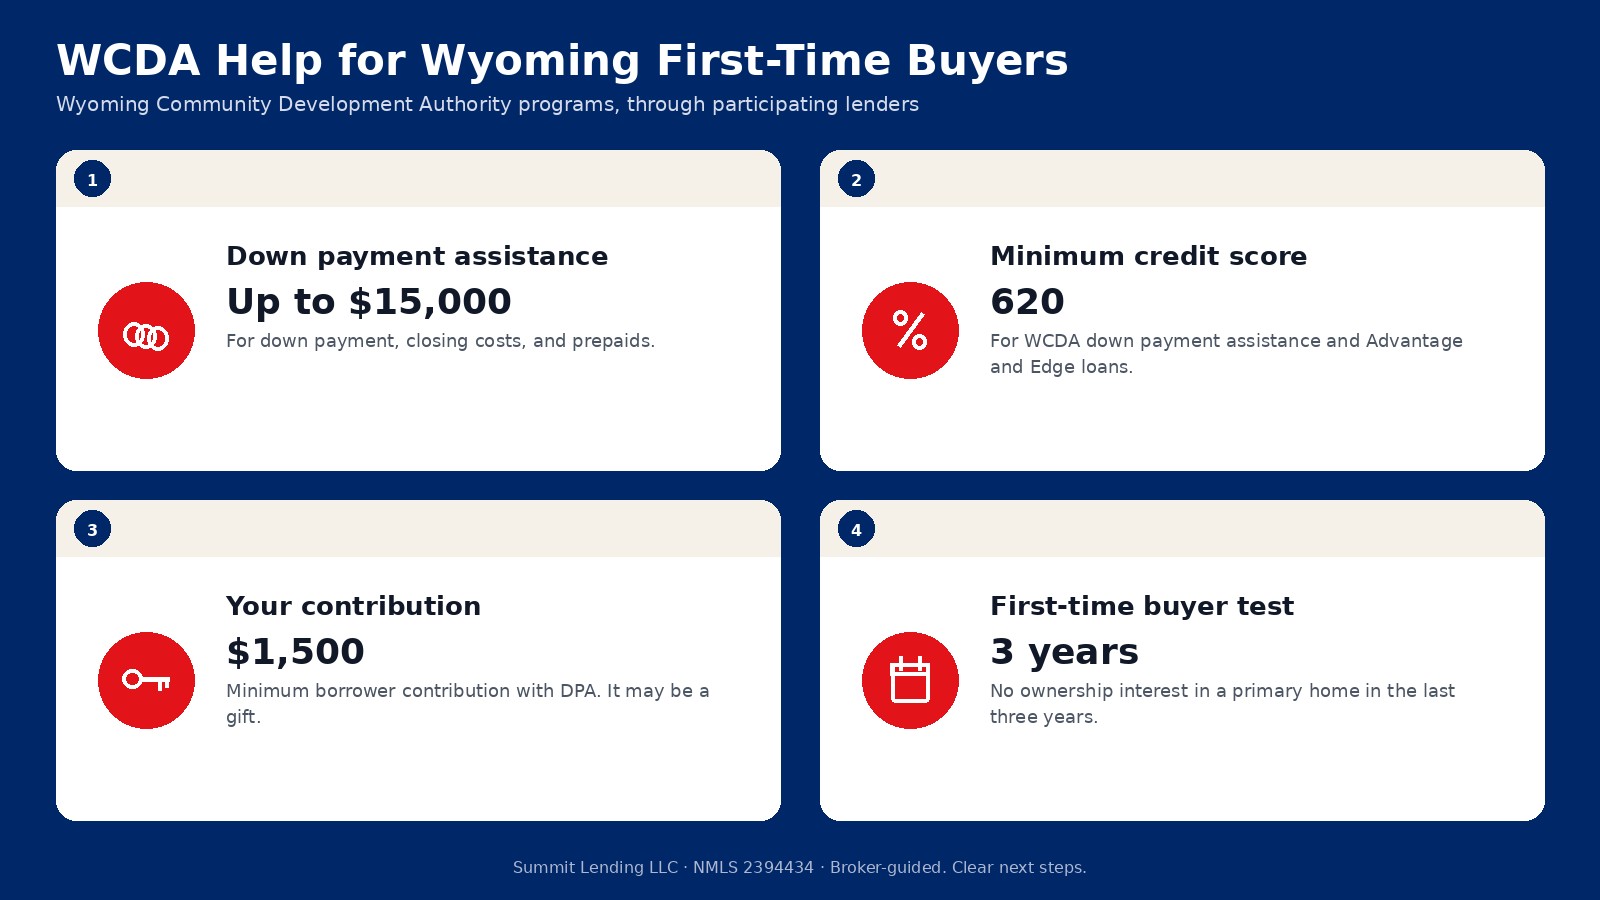
For the Wyoming Community Development Authority's first-time buyer products, you qualify if you have had no ownership interest in a primary residence in the last three years (WCDA homebuyers). So if you owned a home years ago and have rented since, you may still count. Some WCDA products, Advantage and Edge, have no first-time buyer requirement at all.
WCDA programs, in plain language
- Standard First-Time Homebuyer loan. A low fixed-rate, 30-year loan with FHA, VA, or USDA Rural Development financing. You must meet the three-year test, stay within purchase price and income limits, and live in the home as your primary residence. The home must sit on 10 acres or less, and it can be subject to the federal recapture tax (WCDA; WCDA purchase price and income limits).
- Spruce Up. One loan that covers both the purchase and repairs or updates, such as a roof, plumbing, heating, or energy improvements. It follows the first-time buyer rules.
- Advantage and Edge. 30-year fixed loans for purchase or refinance with no first-time buyer requirement and no purchase price limit. Income limits apply, the minimum credit score is 620, you must live in the home for at least a year, and the home must sit on 10 acres or less. They are not subject to the federal recapture tax.
- Mortgage Credit Certificate. A federal income tax credit based on part of the mortgage interest you pay, for qualifying first-time buyers. Its value depends on your own tax situation, and WCDA reimburses borrowers who end up paying recapture tax.
WCDA down payment assistance
WCDA's down payment assistance can cover down payment, closing costs, and prepaid items. Every WCDA DPA loan has a $15,000 maximum, a 620 minimum credit score, and a $1,500 minimum contribution from you, which may come from a gift (WCDA). There are two versions:
- Home$tretch. 0% interest and no monthly payment. It is repaid when you sell, refinance, or reach the end of 30 years. It pairs with the First-Time Homebuyer, Spruce Up, and Edge products.
- Amortizing DPA. A fixed-rate second loan with low monthly payments over a maximum 10-year term, used only with Advantage.
How much does the payment matter? If you used an amortizing DPA loan of $15,000 at a hypothetical 7.28% over 10 years, it would add about $176 a month. Home$tretch adds nothing monthly, but it is still a lien you repay when you sell or refinance. We show both side by side.
Loan options for first-time buyers
- FHA. 3.5% down with a 580 or higher score (HUD FHA overview), with a 1.75% upfront premium and an annual premium (HUD Mortgagee Letter 2023-05).
- Conventional. As little as 3% down for qualified buyers on a one-unit primary home (Fannie Mae eligibility matrix), with PMI below 20% down (CFPB on PMI).
- VA. No down payment and no monthly mortgage insurance for eligible borrowers (VA purchase loans), with a funding fee unless exempt (VA funding fee). Useful near F.E. Warren AFB and Cheyenne.
- USDA. No down payment in eligible rural areas for households under the income limits (USDA guaranteed loans). Much of Wyoming outside the larger cities can qualify, so check addresses on the USDA eligibility map.
The 2026 conforming loan limit is $832,750 for a one-unit home in most of the state and $1,249,125 in Teton County (FHFA). FHA limits vary by county (HUD lookup).
Wyoming's homeowner property tax exemption
Wyoming's Senate File 69, passed in 2025, created a homeowner exemption equal to 25% of fair market value on the first $1,000,000 of value for qualifying owner-occupied homes. You must have lived in the home for at least eight months of the year and file an affidavit (SF0069). The Department of Revenue explains filing and timing for each tax year (Wyoming homeowner exemption). As a first-time buyer, put a reminder on your calendar to file it after you move in, because the seller's exemption does not carry over to you.
Your first Wyoming home, step by step
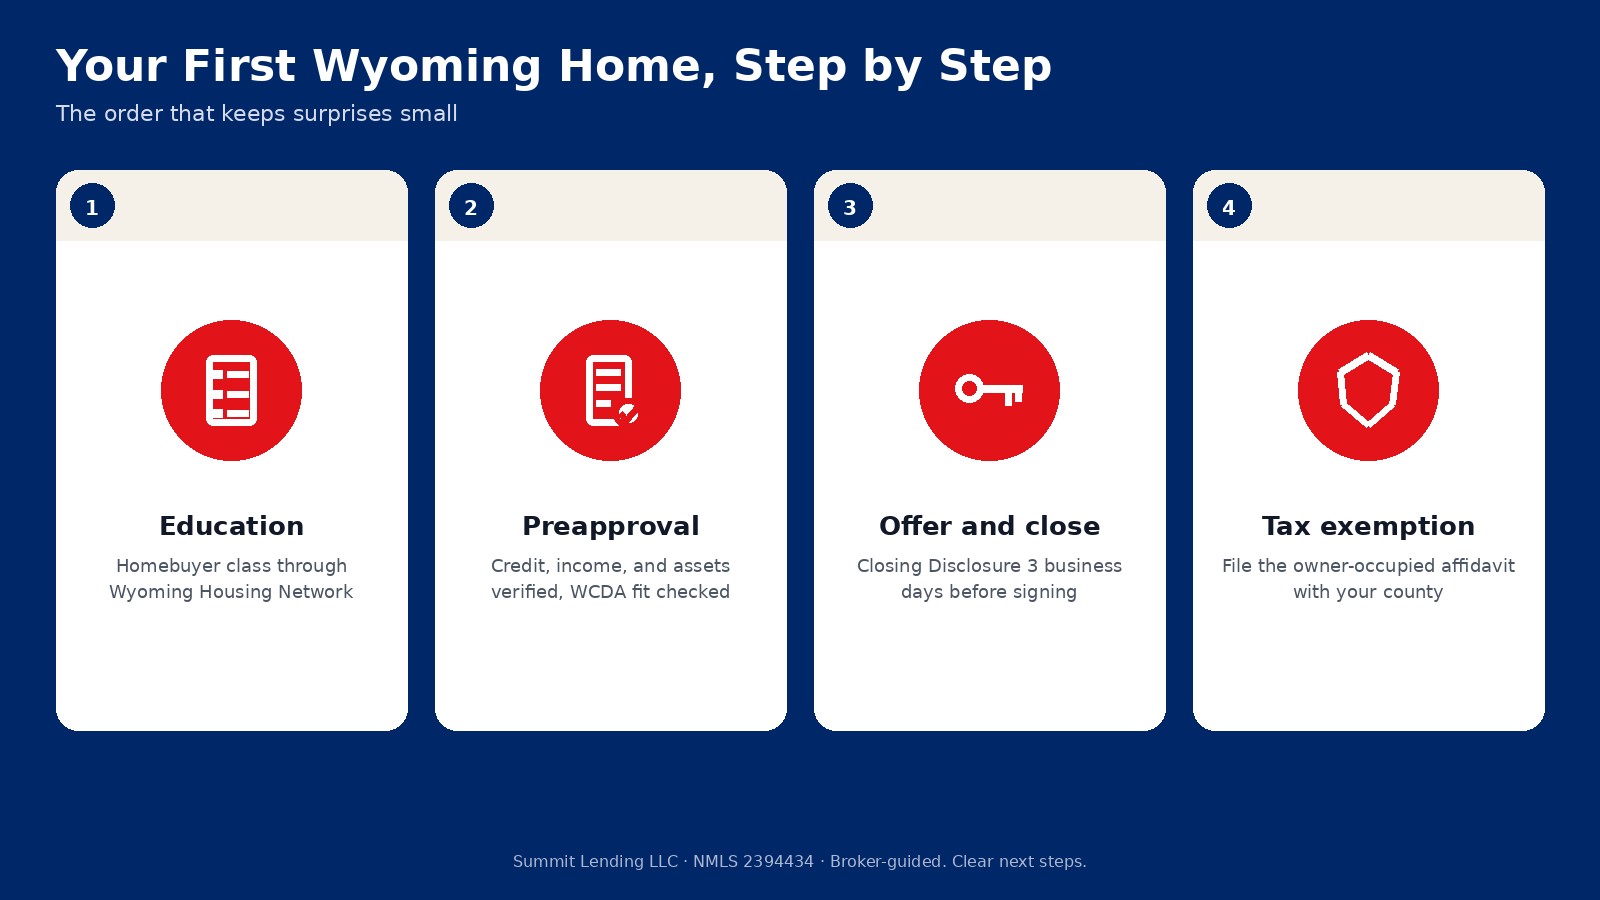
- Take homebuyer education. WCDA requires first-time buyers to complete the homebuyer class through Wyoming Housing Network, Inc. (WCDA). Do it early so it never holds up closing.
- Get preapproved. We verify credit, income, and assets and check which WCDA products and limits fit (CFPB on preapproval). Several mortgage credit checks within 45 days count as one inquiry for most scoring models (CFPB).
- Shop and make an offer. Keep your price inside the program limits you are using.
- Loan Estimate and underwriting. Your Loan Estimate arrives within three business days of applying for a specific property (CFPB on Loan Estimates).
- Close. Your Closing Disclosure arrives at least three business days before you sign (CFPB on Closing Disclosures).
- File the exemption. Submit the owner-occupied affidavit with your county assessor.
Mistakes we see first-time buyers avoid
- Picking a home on more than 10 acres and then learning it does not fit a WCDA loan.
- Waiting until after an offer to start homebuyer education.
- Forgetting that the amortizing DPA payment counts in your debt-to-income ratio (CFPB on DTI).
- Opening new credit or changing jobs between preapproval and closing.
- Budgeting only for principal and interest. In Wyoming, add property tax, insurance, and winter heating costs to your monthly plan.
Where we help first-time buyers in Wyoming
Cities: Cheyenne, Casper, Laramie, Gillette, Rock Springs, Evanston, Cody, Lander, Rawlins, and Powell. Counties: Laramie County, Natrona County, Campbell County, Sweetwater County, Albany County, Sheridan County, Park County, Fremont County, Uinta County, and Lincoln County.
Related pages
See Wyoming purchase loans, the Wyoming mortgage overview, Wyoming refinancing, and the national first-time home buyer guide. We also help first-time buyers in Utah, Idaho, and Texas.
Sources
- Redfin, Wyoming housing market
- Freddie Mac PMMS, Oct 1, 2026 release
- Freddie Mac Primary Mortgage Market Survey
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- HUD, Let FHA loans help you
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- VA purchase loan
- VA funding fee and closing costs
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- FHFA, 2026 conforming loan limits
- HUD FHA mortgage limits lookup
- Wyoming SF0069 (2025), homeowner tax exemption (PDF)
- Wyoming Department of Revenue, homeowner exemption
- CFPB, prequalification vs. preapproval
- CFPB, when a lender checks your credit
- CFPB, What is a Loan Estimate?
- CFPB, What is a Closing Disclosure?
- CFPB, debt-to-income ratio
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.

Our Process Is Straightforward
With Summit Lending, you can be rest assured that our mortgage loan experts will guide you throughout the process, from exploring your loan options to approval.