Wyoming Mortgage Preapproval

Your Guide To Home Loan Pre Approval in Wyoming
What Are Mortgage Loan Pre-Approvals?
A home loan pre-approval serves as a stamp of approval from lenders confirming your financial readiness to buy a home. Before you get pre-approved, the lender will evaluate your debt-to-income ratio and creditworthiness. Upon approval, you will receive a statement that serves as their conditional commitment to lending you money to buy your home while also showing how much they are willing to give you.
Pre-approval Vs Prequalification - What's The Difference?
A prequalification gives you a rough idea of how much you can borrow based on what you tell the lender about your finances. Pre-approval, on the other hand, means the lender has checked and confirmed your financial information, giving you a conditional thumbs-up for a specific loan amount.
When Should You Get Pre-Approved?
You can get approved for a mortgage in as little as one business day if your paperwork is in order, while other lenders may take longer. Pre-approvals are usually valid for 90 days. However, some lenders may keep it valid for 30 or 60 days.
We recommend you start before looking for a home to ensure you can make an offer on the home you like on time.
Do Pre-approvals Affect Your Credit Score?
Before you get preapproved for a mortgage, lenders carry out a hard pull of your credit to check your score, temporarily lowering it by a few points. However, you will have a 45-day window in which multiple credit score inquiries will be considered on your credit report. Are you worried about denial? You can ask the lender why your home loan pre approval was denied and address the issue.
However, when you work with mortgage loan specialists like us, we ensure you apply for the loans that best align with your financial situation, maximizing your chances of approval.
Pre-Approval Costs in Wyoming
You may be wondering if you need to pay money to get pre-approved for a mortgage loan in Wyoming. That depends on the lender you choose to work with. Some do it for free, while others demand a non-refundable application fee you must pay upfront, whether you get approved or not.
Buying your first home?
3% down on conventional loans, 3.5% with FHA
We line up down payment assistance, credit prep and pre-approval for first-time buyers, so you know your payment and cash to close before you make an offer.
See first-time buyer optionsGet preapproved for a Wyoming mortgage
A mortgage preapproval is a lender's written statement of how much it is willing to lend you, based on a review of your credit, income, assets, and debts. In Wyoming, where many towns have a short list of homes for sale and good listings move quickly in spring and summer, a preapproval letter shows a seller that your offer is real. It also tells you, before you fall for a house, what price range and monthly payment actually work for you. Summit Lending LLC (NMLS 2394434) is a mortgage broker licensed in Wyoming. We compare loan options across lenders and help you get a preapproval you can rely on, whether you are buying in Cheyenne, Casper, Laramie, Gillette, or a smaller town.
Summit Lending LLC, NMLS 2394434, is based at 4542 W 14800 N, Garland, UT 84312 and serves borrowers in Utah, Texas, Idaho, Wyoming, Arkansas, and Arizona. Call 385-200-1470 or email [email protected].
Prequalification vs. preapproval
The terms are often used loosely, and the CFPB notes that lenders do not always use them the same way (CFPB on preapproval). In general:
- Prequalification is a quick estimate based on what you tell the lender. It may not include a credit check or document review.
- Preapproval is based on a credit report and verified income and assets. It still depends on the home, the appraisal, and final underwriting, but it carries much more weight with sellers and listing agents.
Ask exactly what was verified. A strong letter names the loan type and price range, and the lender behind it should be able to explain any conditions.
What lenders look at
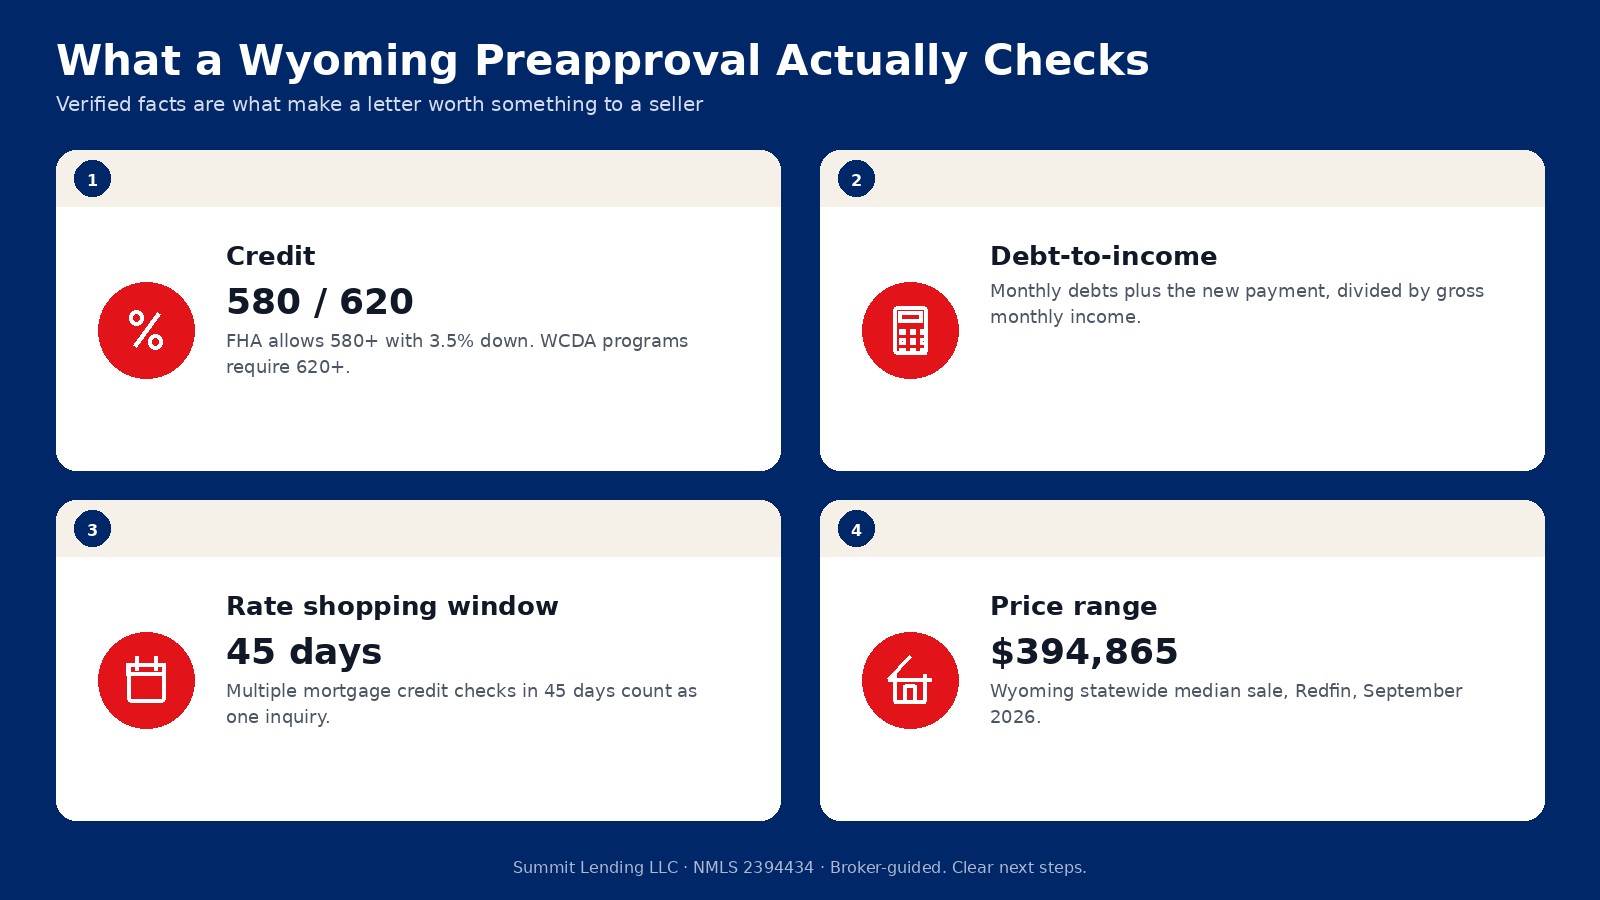
- Credit. FHA allows a 3.5% down payment with a credit score of 580 or higher (HUD FHA overview). WCDA's homebuyer programs require a minimum score of 620 (WCDA). Higher scores usually mean better pricing on conventional loans. Check your reports for errors before you apply (CFPB on credit scores).
- Debt-to-income ratio. Your monthly debts plus the new housing payment, divided by your gross monthly income (CFPB on DTI). The new payment includes property tax, homeowners insurance, and any mortgage insurance or HOA dues.
- Income and employment. Usually two years of history. Wyoming has many energy, mining, ranching, and seasonal workers, and variable income such as overtime, bonuses, or per diem can count if it is documented and likely to continue. Self-employed borrowers typically need two years of tax returns.
- Assets. Money for the down payment, closing costs, and sometimes reserves. Gifts from family are allowed on most loans with a gift letter.
Wyoming preapproval document checklist
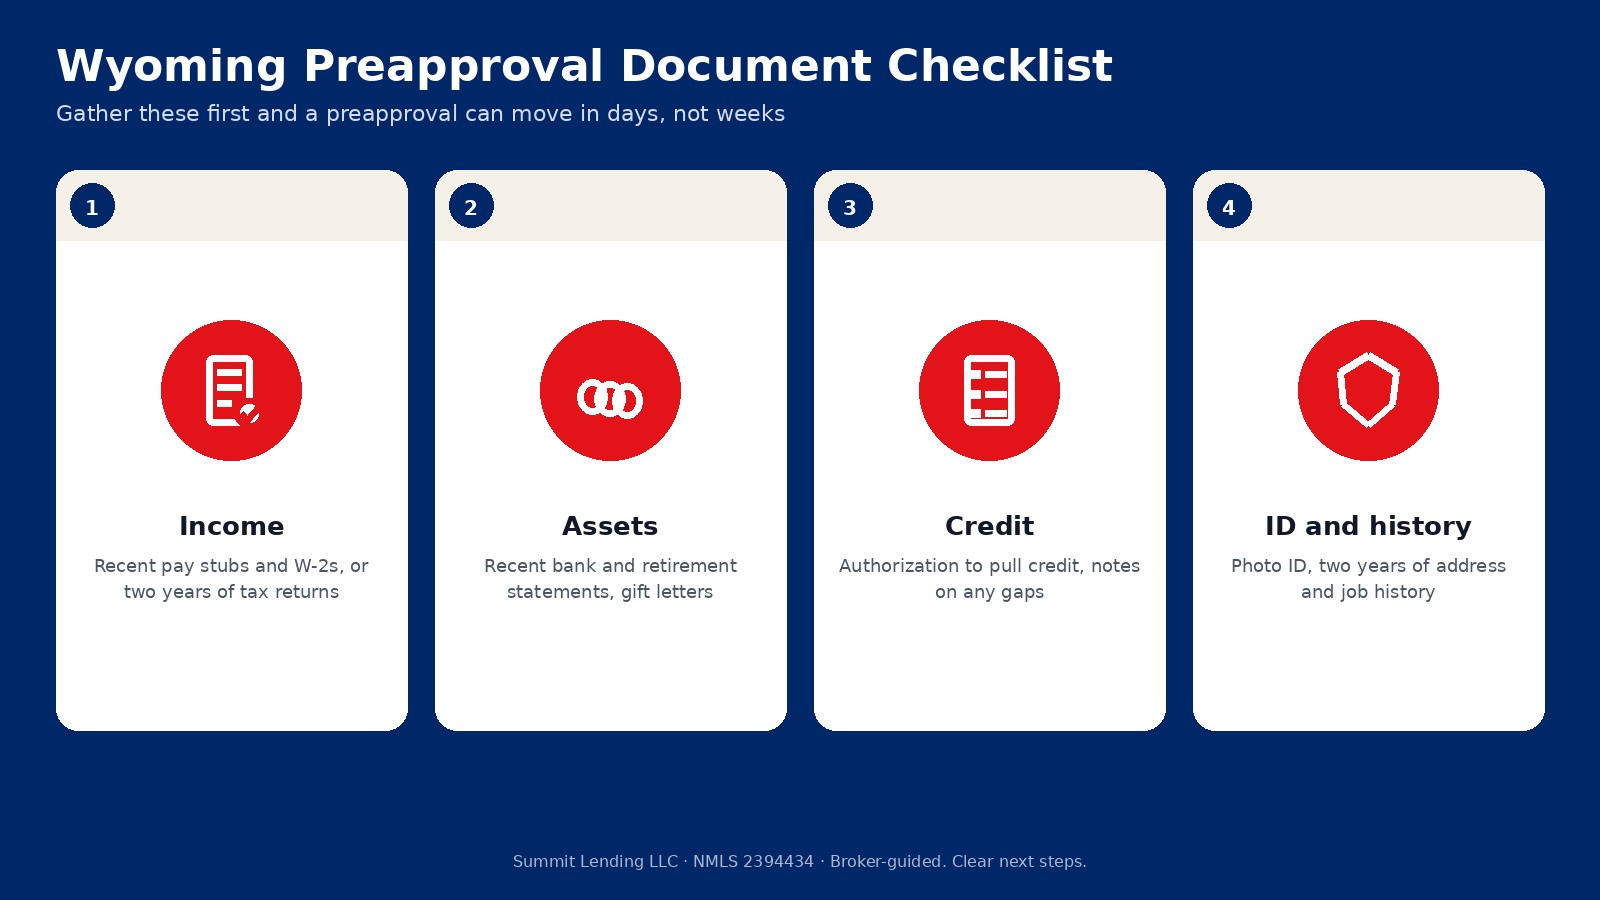
- Income. Pay stubs covering the last 30 days, W-2s for two years, or two years of personal and business tax returns if you are self-employed. Add award letters for Social Security, pension, or VA income.
- Assets. Two recent months of bank statements, plus retirement or investment statements. Explain large deposits that are not payroll.
- Credit. Authorization to pull credit, and short written explanations for late payments, collections, or recent inquiries.
- ID and history. Photo ID, two years of addresses, and two years of employers. If you are a veteran, your Certificate of Eligibility helps (VA eligibility).
Shopping lenders without hurting your credit
Rate shopping is smart. Credit scoring models generally treat multiple mortgage credit checks within a 45-day window as a single inquiry, so comparing offers over a few weeks has little extra impact on your score (CFPB). Compare the Loan Estimate each lender gives you, especially the rate, points, and lender fees in Section A (CFPB on Loan Estimates). As a broker, we can request pricing from several lenders on the same scenario.
Rates matter more than usual right now. Freddie Mac's survey put the 30-year fixed average at 7.40% for the week of October 8, 2026, up from 7.28% the week before and 6.30% a year earlier (AP report on the Freddie Mac survey; Freddie Mac PMMS). A preapproval at today's rates protects you from shopping above what you can comfortably afford.
Wyoming numbers that shape your preapproval
- Home prices. Redfin put the Wyoming statewide median sale price at about $394,865 for September 2026, up 8.9% from a year earlier (Redfin Wyoming data). Prices vary widely, from smaller towns well under the median to Teton County, where values far exceed it.
- Loan limits. The 2026 conforming limit for a one-unit home is $832,750 across Wyoming (FHFA). The FHA limit for a one-unit home is $541,287 in most Wyoming counties, with a higher limit in Teton County (HUD FHA limit lookup).
- Property tax. Residential property is assessed at 9.5% of market value (Wyoming Property Tax Division). Owner-occupied homes can be exempt on 25% of value up to the first $1,000,000 if you apply with your county assessor (Wyoming SF0069 summary; application portal). Lenders estimate taxes in your payment, so ask how the exemption will be treated once you own the home.
- Insurance. Hail and wildfire risk affect premiums. Get a quote early in high-risk areas so the payment in your preapproval is realistic.
- Rural property. Homes on acreage or outside town may qualify for USDA loans with no down payment (USDA Single Family Housing; check the eligibility map). Wells, septic systems, and access roads can add appraisal and inspection conditions.
Loan options to discuss
- Conventional. As little as 3% down for some first-time buyers (Fannie Mae). Private mortgage insurance applies below 20% down and can be removed later (CFPB on PMI).
- FHA. 3.5% down with a 580 score. Annual mortgage insurance is 0.55% for most borrowers (HUD Mortgagee Letter 2023-05).
- VA. No down payment for eligible veterans and service members, including those at F.E. Warren Air Force Base near Cheyenne (VA home loans; VA funding fee).
- USDA. No down payment in eligible rural areas, which covers much of Wyoming.
- WCDA programs. The Wyoming Community Development Authority offers first-time buyer loans and down payment assistance, with income and purchase price limits (WCDA; WCDA limits). See Wyoming first-time buyer loans.
How long a preapproval lasts
Most preapproval letters are good for 60 to 90 days, because the credit report and pay stubs behind them age. If you are still shopping after that, we update the documents and reissue the letter. Avoid new debt, large unexplained deposits, and job changes while you are shopping and after you go under contract, since the lender will check again before closing (CFPB on closing).
Preapproval across Wyoming
Cities and towns: Cheyenne, Casper, Laramie, Gillette, Rock Springs, Teton Village, and Fort Laramie. Counties: Laramie County, Natrona County, Campbell County, Sweetwater County, Albany County, Teton County, and Sheridan County.
Related pages
Run numbers with the Wyoming mortgage calculator, or the city calculators for Cheyenne and Casper. See Wyoming purchase loans, the Wyoming mortgage overview, the Wyoming refinance page, the Wyoming commercial loans page, and preapproval in Utah, Idaho, and Texas.
Sources
- Redfin, Wyoming housing market
- AP via WTOP, Freddie Mac rates for Oct 8, 2026
- Freddie Mac Primary Mortgage Market Survey
- CFPB, prequalification vs. preapproval
- HUD, Let FHA loans help you
- Wyoming Community Development Authority, homebuyers
- WCDA purchase price and income limits
- CFPB, when a lender checks your credit
- CFPB, debt-to-income ratio
- VA home loan eligibility
- CFPB, What is a Loan Estimate?
- FHFA, 2026 conforming loan limits
- HUD FHA mortgage limits lookup
- Wyoming DOR Property Tax Division, residential
- Wyoming Legislature, 2025 SF0069 bill summary (PDF)
- Wyoming owner-occupied exemption application
- USDA Single Family Housing Guaranteed Loan Program
- USDA property eligibility map
- Fannie Mae Eligibility Matrix
- CFPB, private mortgage insurance
- HUD Mortgagee Letter 2023-05, FHA annual MIP (PDF)
- VA purchase loan
- VA funding fee and closing costs
- CFPB, What is a Closing Disclosure?
Information on this page is for general education and is current as of October 2026. It is not a commitment to lend or a rate quote. Program rules, limits, and availability change, and approval depends on your credit, income, assets, property, and lender guidelines. Summit Lending LLC, NMLS 2394434. Equal Housing Opportunity.